Your Insurance Claim, Documented Right — From the First Hour.
Water, fire, mold & asbestos losses in Rockford, IL. We photograph everything, write the estimate in Xactimate — the same software your adjuster uses — and walk the job with your adjuster. You stay in control of your claim.
Call (815) 721-3493 · Free Claim Walkthrough
IICRC Certified Firm · Xactimate Estimates · 5.0 ★ Google (124 reviews) · Rockford-owned since 2021
Why I Work Late on Your Claim
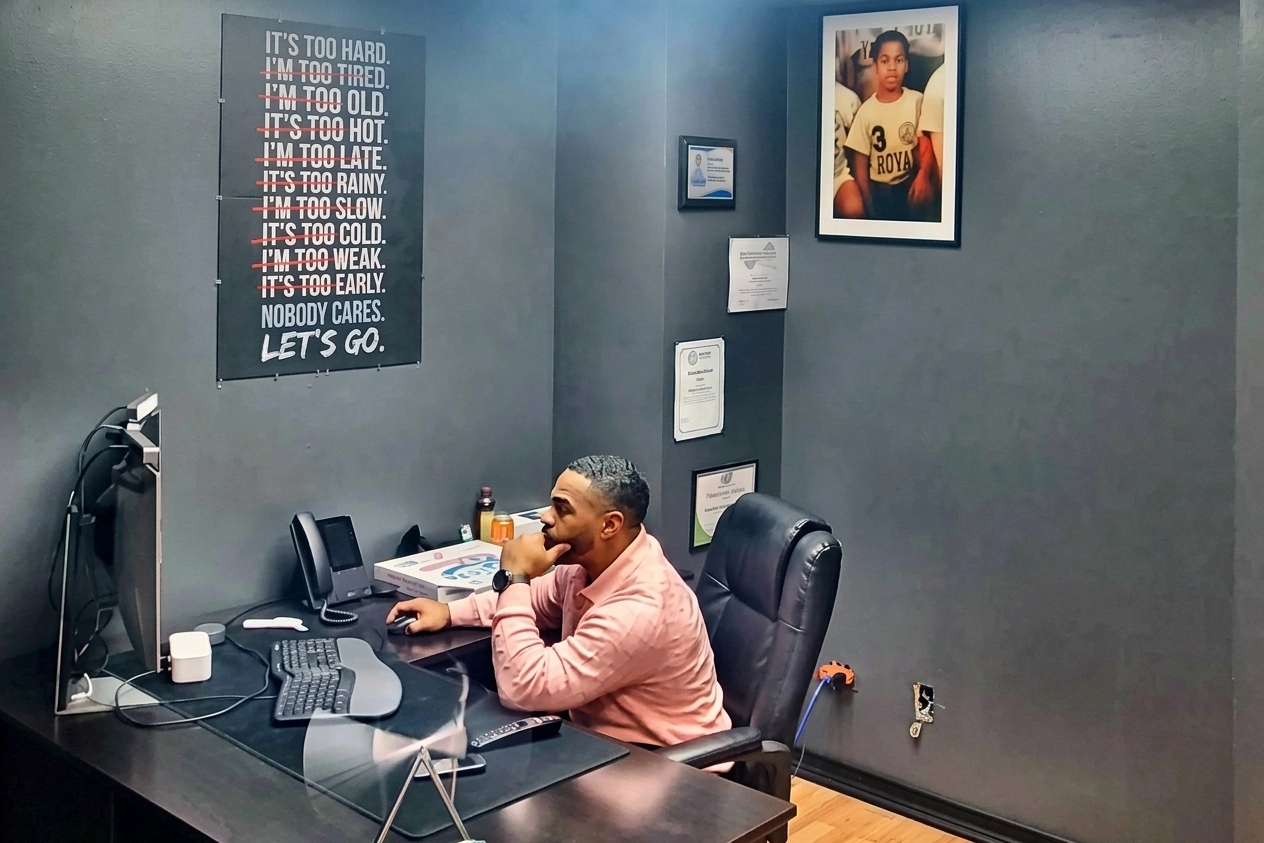
I'll be honest with you: a lot of the work on your claim happens after dark. Once the crew is done for the day, I'm at my desk organizing every photo, every moisture reading and every piece of documentation from your loss — sometimes until the wee hours.
Here's why. Accuracy is the single most important thing in the insurance claim process. Our number one goal is to submit an accurate, fully documented claim to your particular insurance carrier — not a rushed one, not an inflated one, an accurate one. That's what gets approved without a fight, and sometimes getting it right takes staying up late.
I also know what you're going through. A homeowner dealing with a flooded basement or a house fire is at a low point. The time it takes us doesn't matter. Your time — and getting your life back in order — comes first.
— Ramon Darby, Owner, Power Restoration of Rockford
What We Do On Your Claim
Five things that happen on every insured water, fire, mold or asbestos loss we handle in Rockford — so your carrier receives an accurate, fully documented claim the first time.
1. Same-Day Mitigation
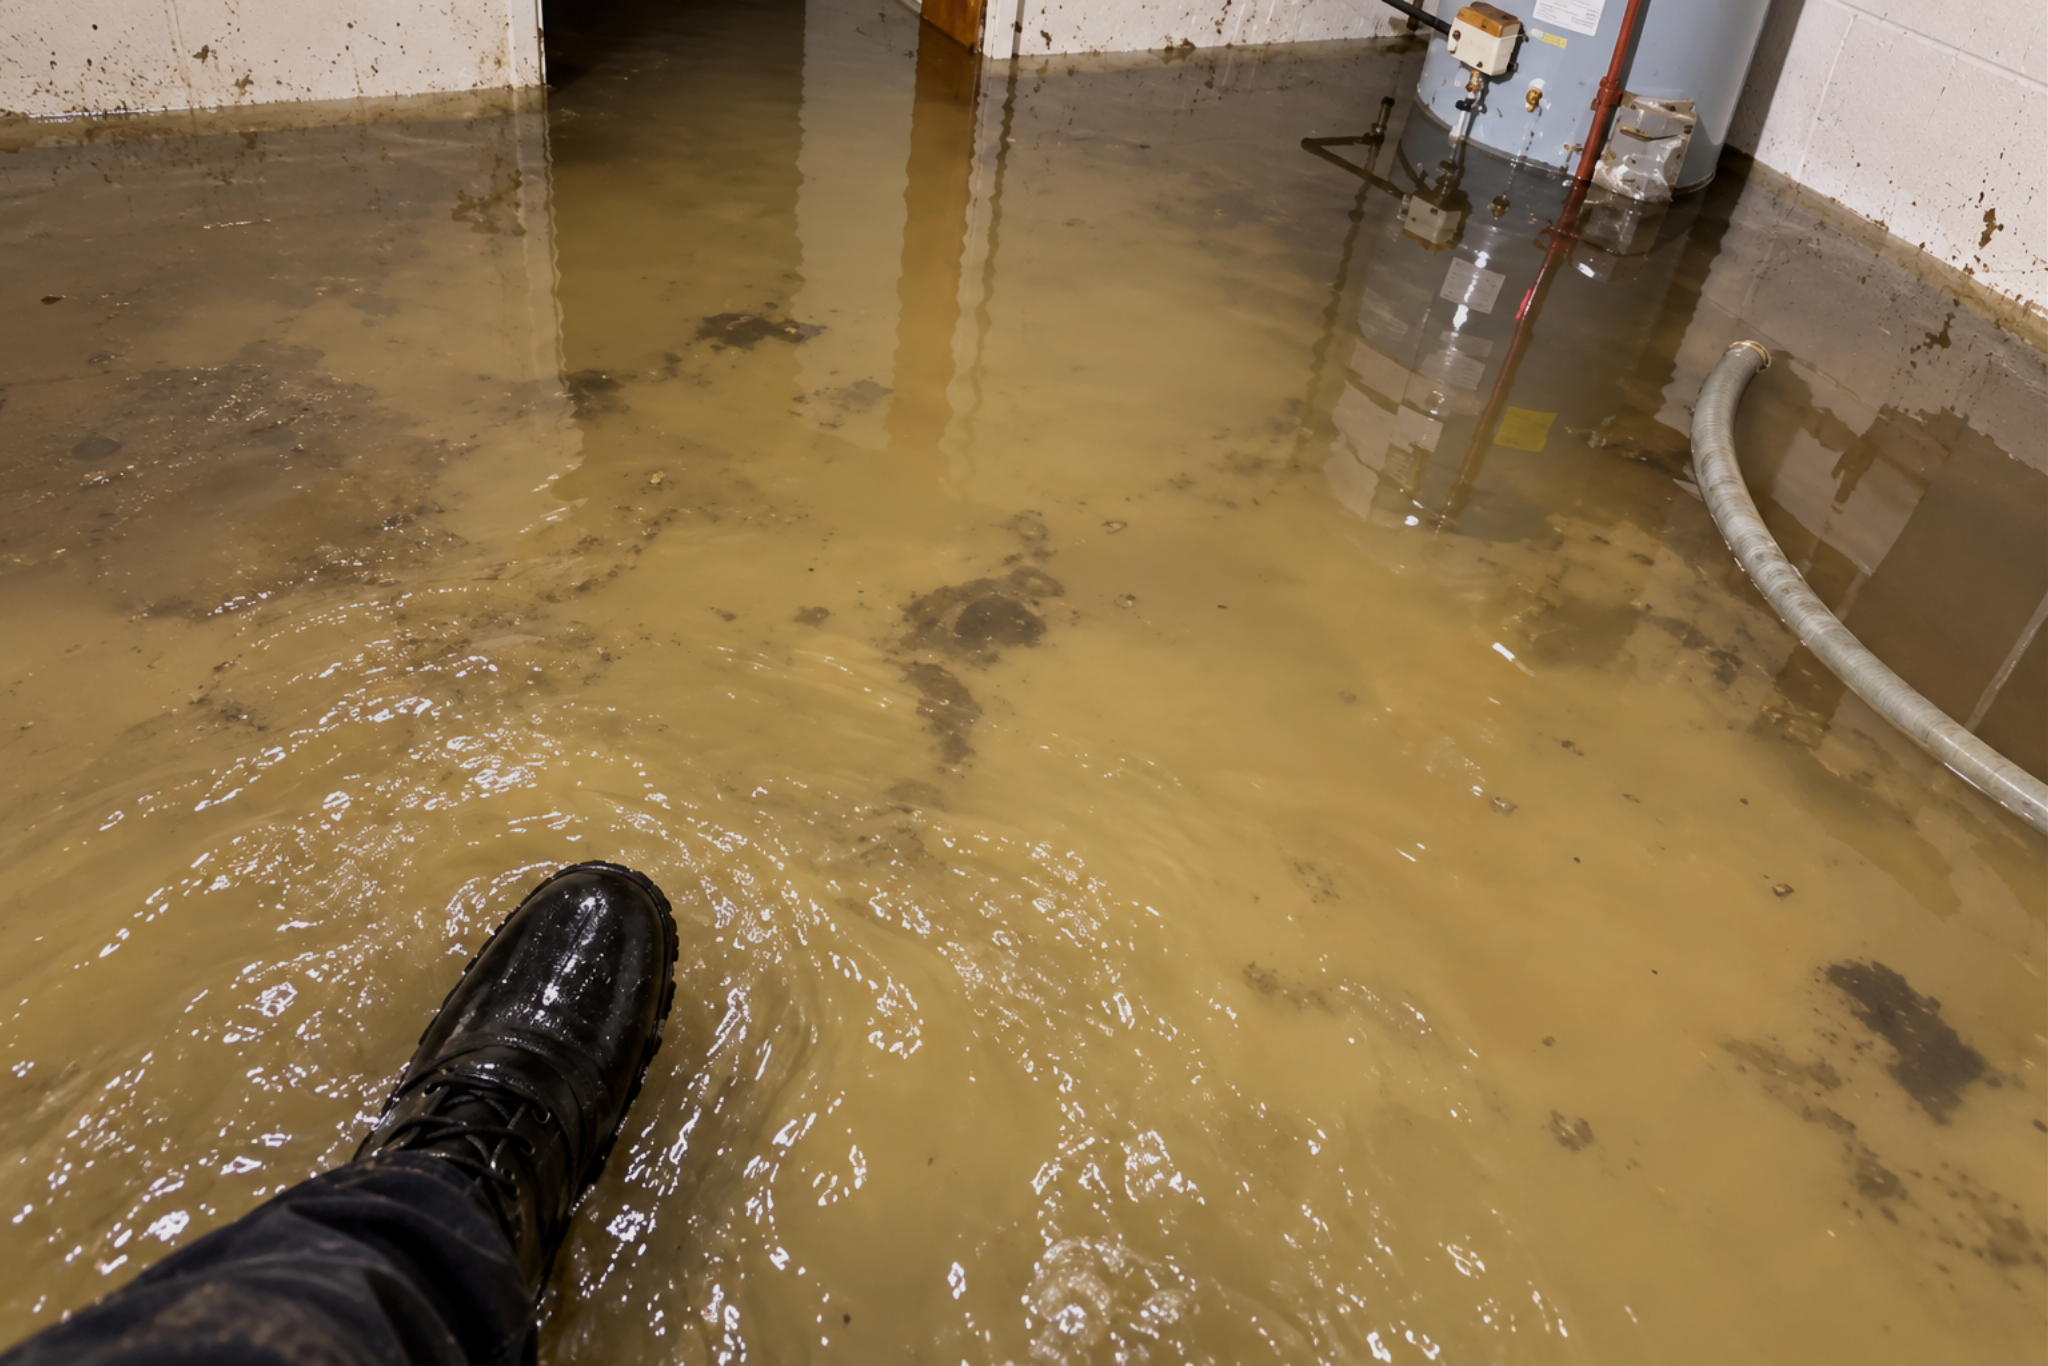
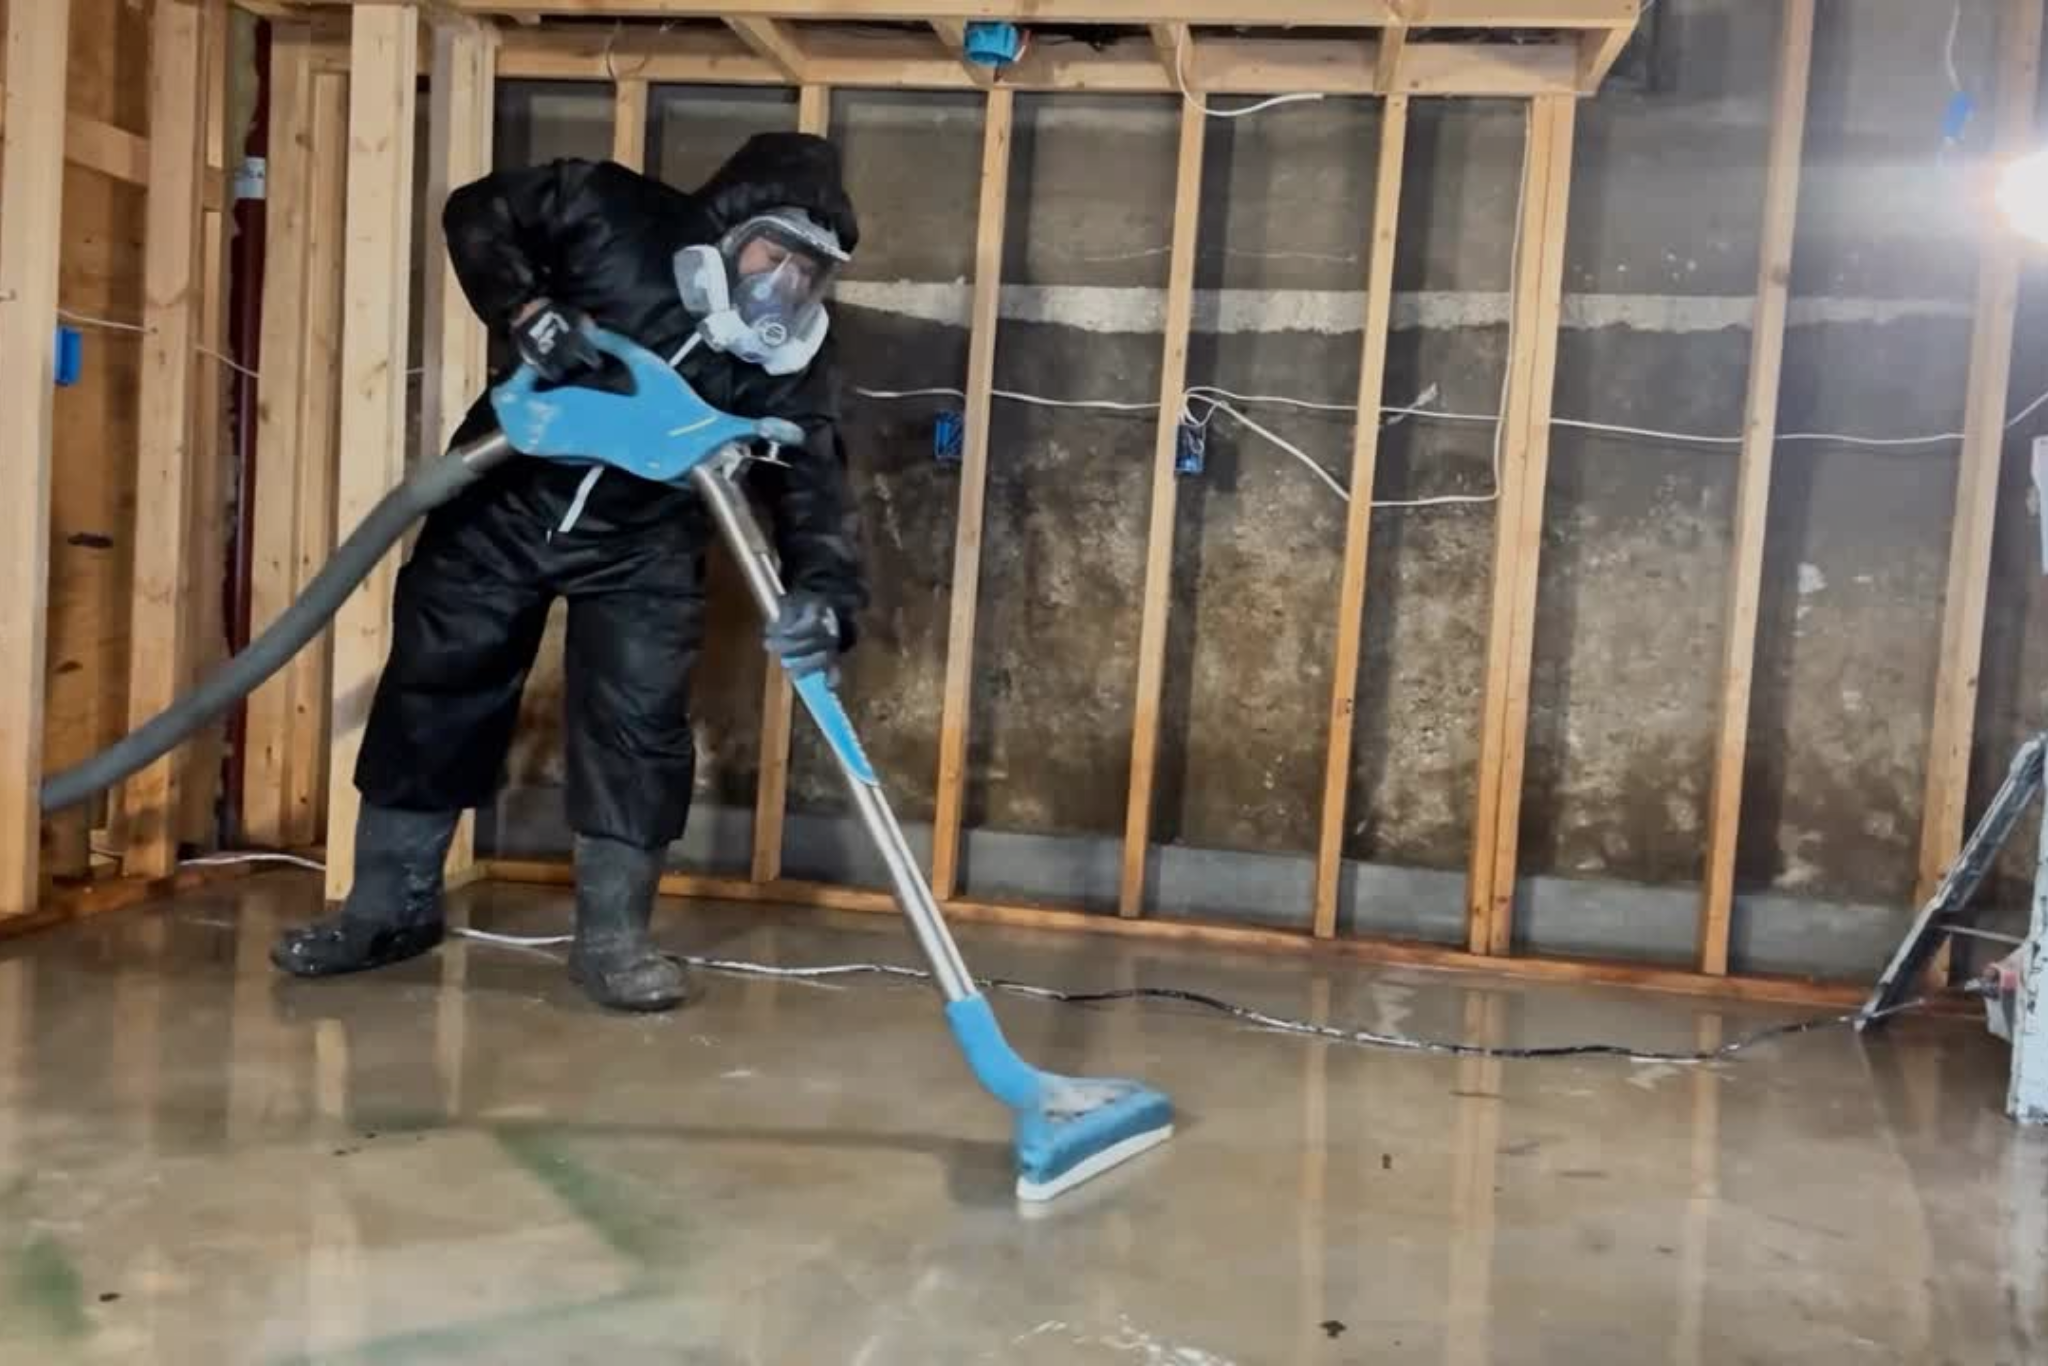
Your policy requires you to protect the property from further damage. We extract water, stabilize the structure and start drying the same day — and we document that we did, which is the first thing an adjuster checks.
2. Photograph & Video Everything
Every room, every affected material, every piece of contents — before, during and after. Hundreds of labeled photos per loss, so nothing is left to "take our word for it."
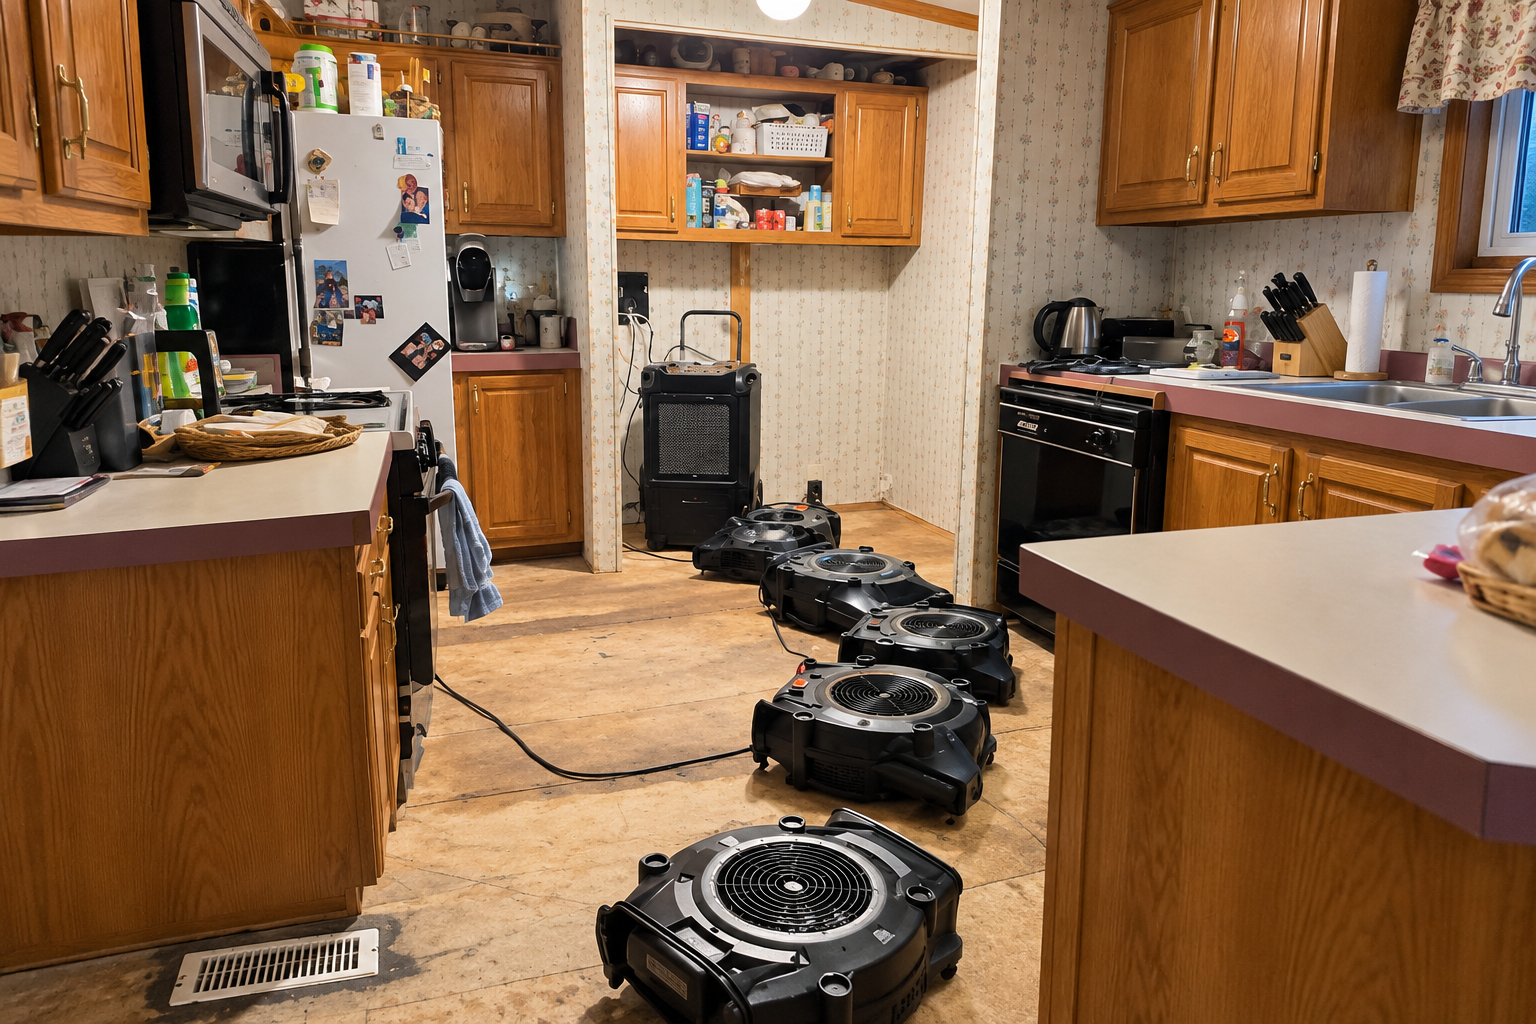
3. Daily Drying Logs
Moisture readings, equipment counts and humidity logs recorded every day the equipment runs. These logs are what justify the drying days on your claim.
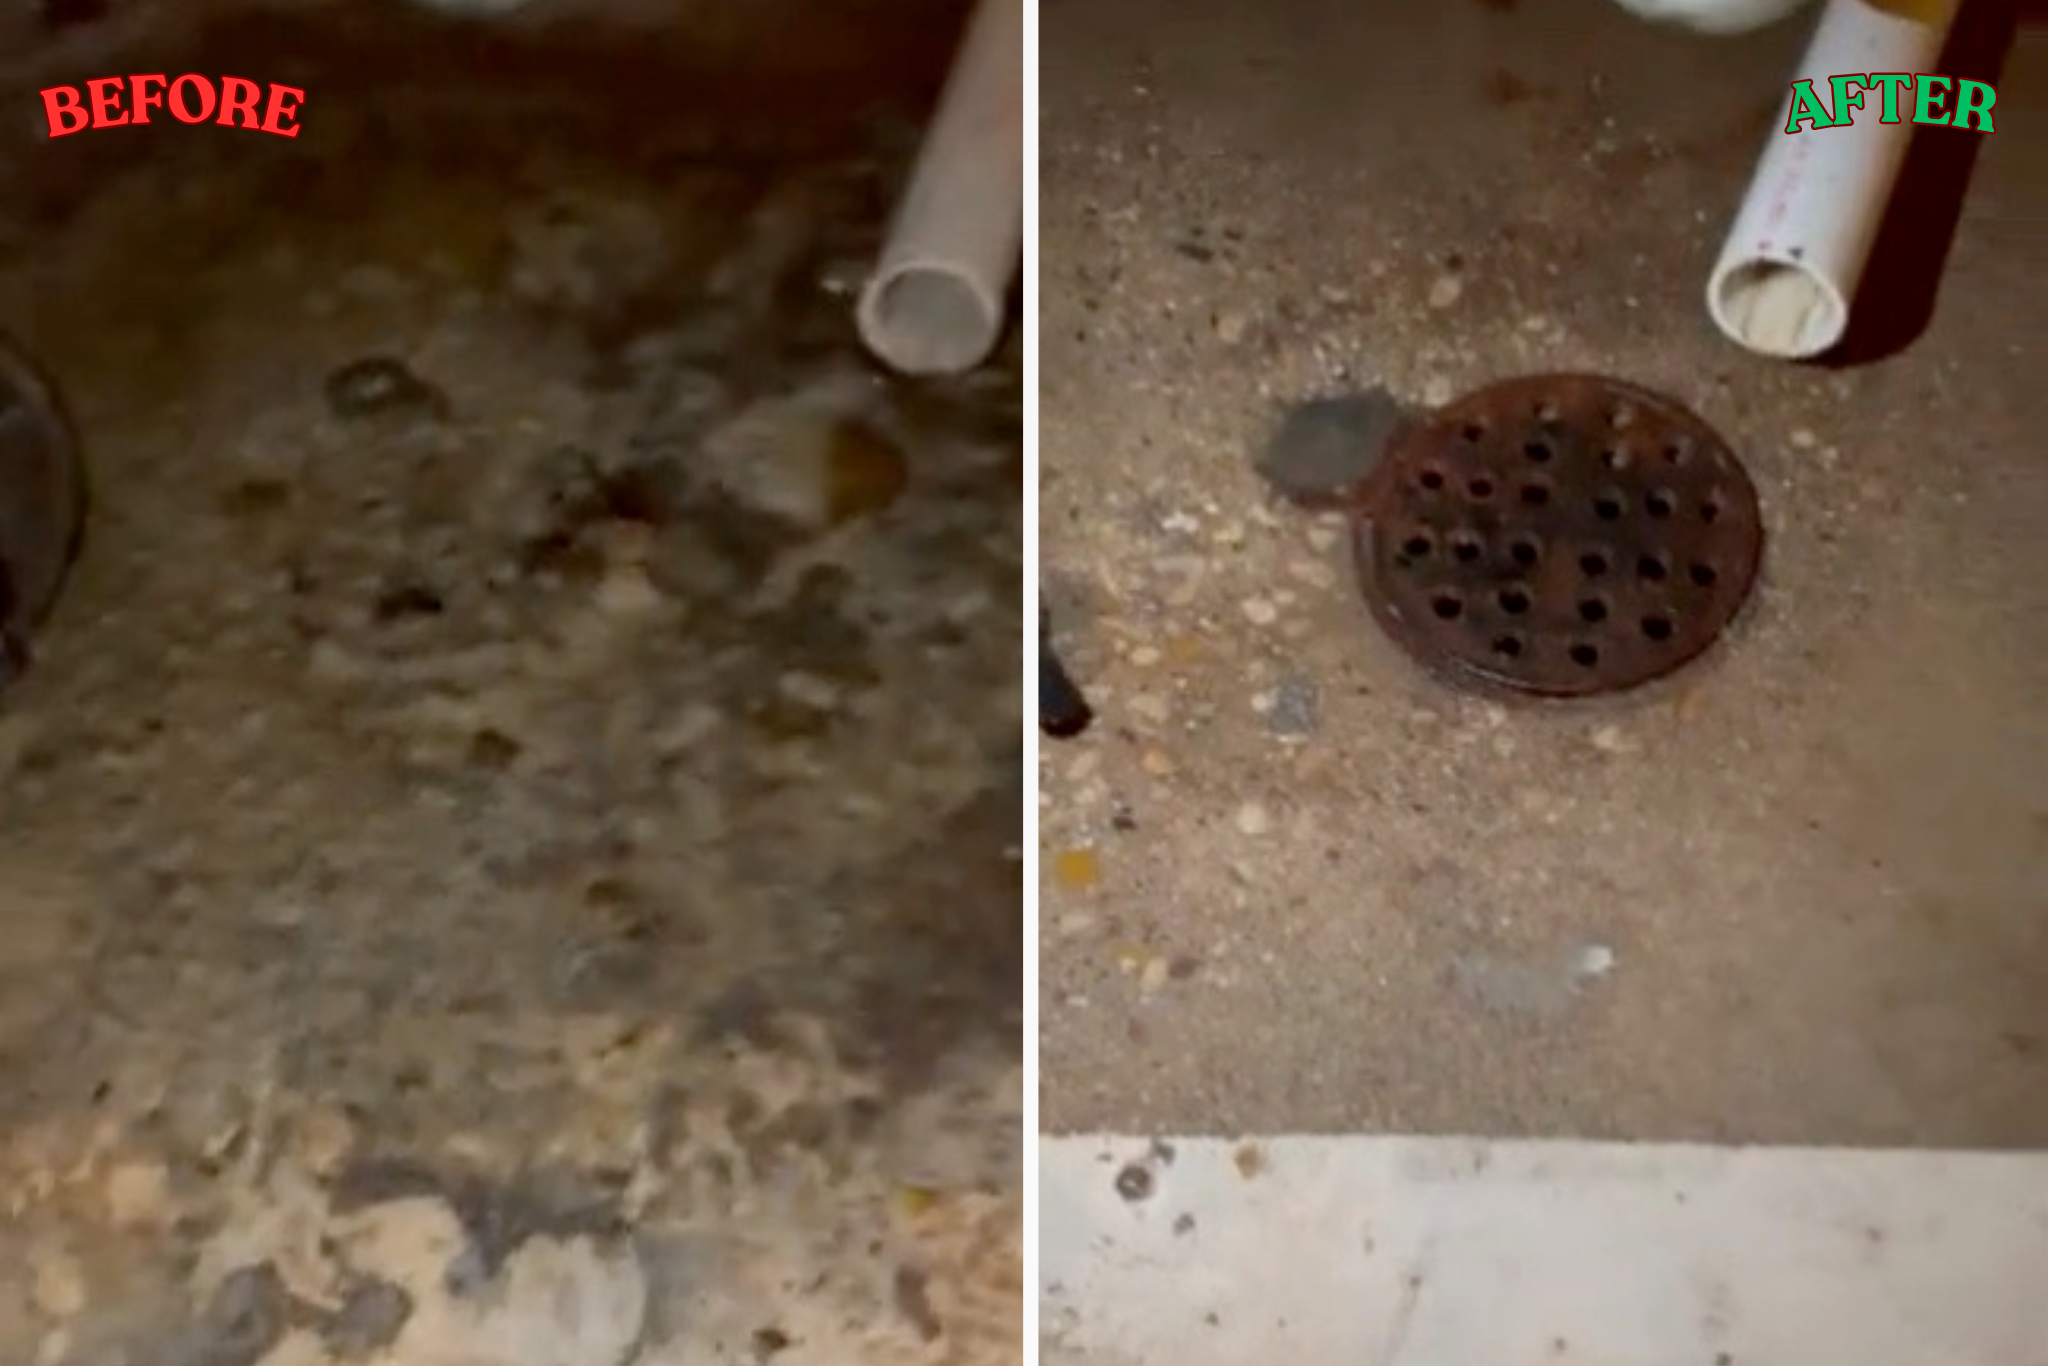
4. Xactimate Estimate, Line by Line
Your estimate is written in Xactimate — the same software your insurance carrier uses — with a photo and note behind every line item. Accurate quantities, correct categories, no surprises.
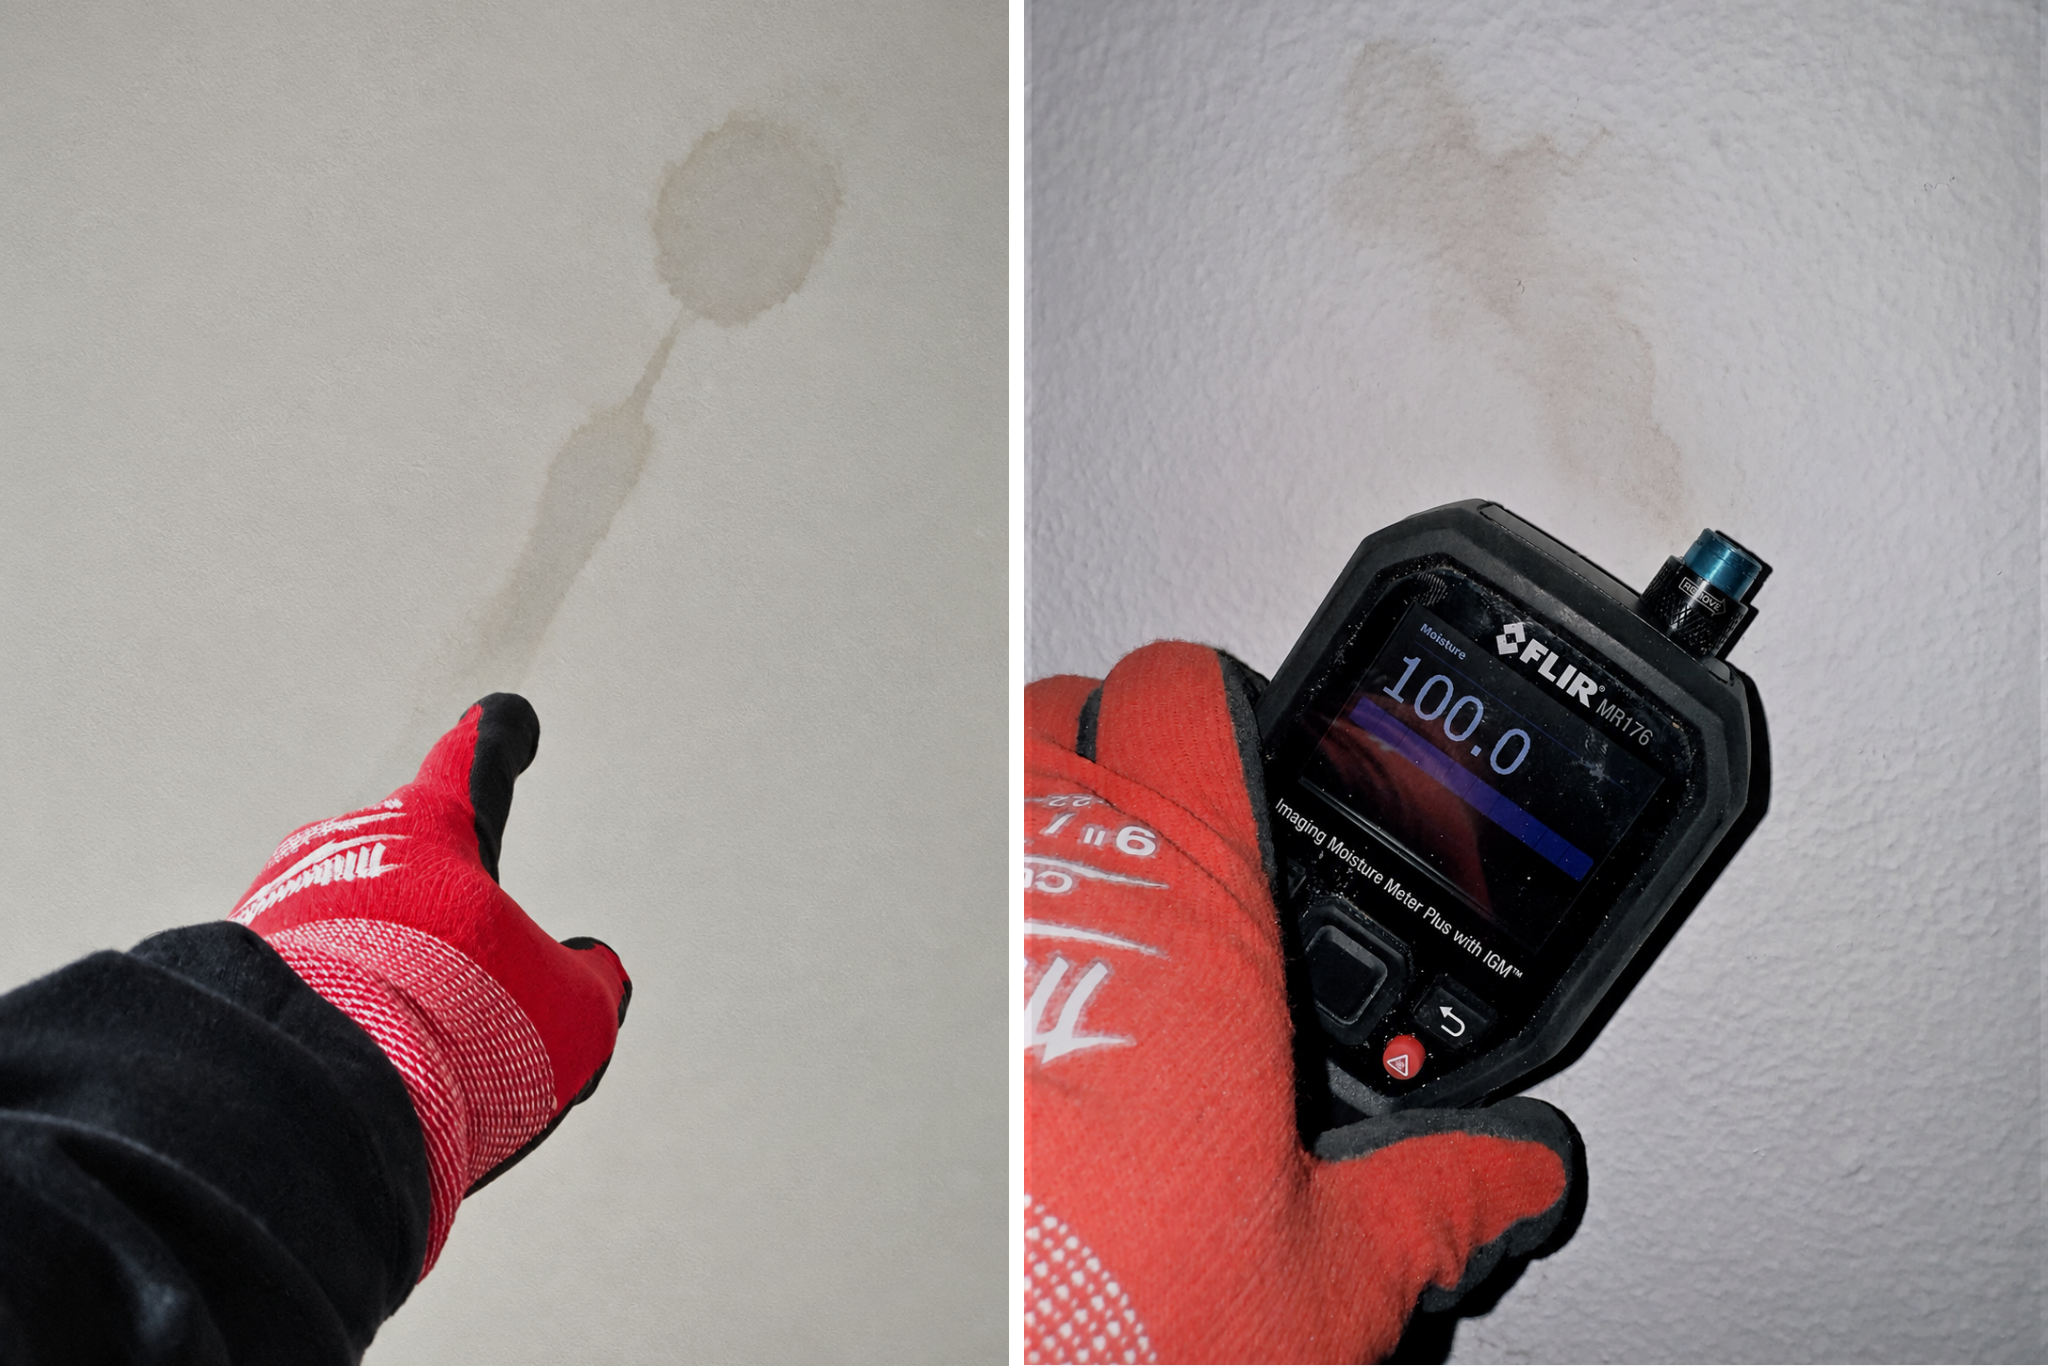
5. Adjuster Walkthrough & Supplements
We meet the adjuster on site, walk the loss with them and answer their questions. If hidden damage turns up during the work, we document it and submit a supplement — you stay in control of every decision.
Insurance Claim Questions Rockford Homeowners Ask Us
Straight answers about the claim process — what to do first, what your policy usually covers, and what happens when the adjuster's numbers don't match ours.
It happens, and it usually comes down to missing information rather than real disagreement. Because every line in our Xactimate estimate has a photo, a moisture reading or a drying log behind it, we send the adjuster the exact documentation that supports the items in question — and most differences close right there.
If a true coverage dispute remains, the next step is yours to make, and you will have the complete documented file to make it with. We do not negotiate your claim for you; in Illinois only a licensed public adjuster or attorney can. What we do is make sure your carrier is deciding from an accurate, complete picture of the loss.
Usually covered (sudden and accidental): burst or frozen pipes, washing machine and dishwasher supply line breaks, water heater failures, toilet overflows, ice-maker lines, roof leaks opened by a storm, and the water used to put out a fire.
Usually not covered: outside flooding and groundwater seeping through foundation walls (that takes separate flood insurance), sewer and sump pump backups unless you bought the Water Backup endorsement, gradual leaks that went on for weeks, and anything blamed on wear, rot or lack of maintenance. Mold is typically covered only when it followed a covered sudden loss, and most policies cap it.
Your adjuster makes the coverage decision. Our job is to make sure the facts of your loss are documented accurately so that decision is made on complete information.
Call us first if water is still running or spreading — your policy requires you to protect the property from further damage, and every hour of delay grows the loss. Then call your carrier's claim line the same day and write down the claim number and your adjuster's name. We photograph and document everything before anything is moved, so your claim starts with a complete record of the damage exactly as it was found.